Annually, L&I reviews your company’s claim history and reported hours to calculate your Experience Modification Rate (EMR).
The Experience Rating Calculation sheet gives you a “preview” of your premium rate and EMR for all of your active L&I accounts (main account and any applicable sub-accounts). The preliminary information is released late September/early October and finalized in December.
Approach has assembled the following step-by-step instructions to help you review your Experience Rating Calculation. View them here.
Remember, the lower your EMR, the less you pay to L&I each quarter in premium.
The best way to control your company’s EMR is to diligently work with your Approach Claims Analyst. In addition to emphasizing injury prevention through a proactive safety program, light-duty and kept-on-salary are very important tools that can help you maintain or lower your EMR.
What is an Experience Modification Rate?
Each employer is assigned a rating which is a numerical value based on your past claims that estimate what a company’s future claims are likely to cost. This number is referred to as an experience modification rating (EMR).
Every employer starts at the base rate value of 1.000, which is the “average” for an industry.
If an employer has a good safety program and proactively manages claims, they can reduce their EMR below 1.000 and receive a discounted insurance premium.
As you can see, the financial impact of an EMR over the base rate of 1.000 is significant.
| EMR | Annual Premium |
| .60 | $45,000 |
| 1.000 (base rate) | $75,000 |
| 1.25 | $93,750 |
How the Dates of Injury Impact Your EMR
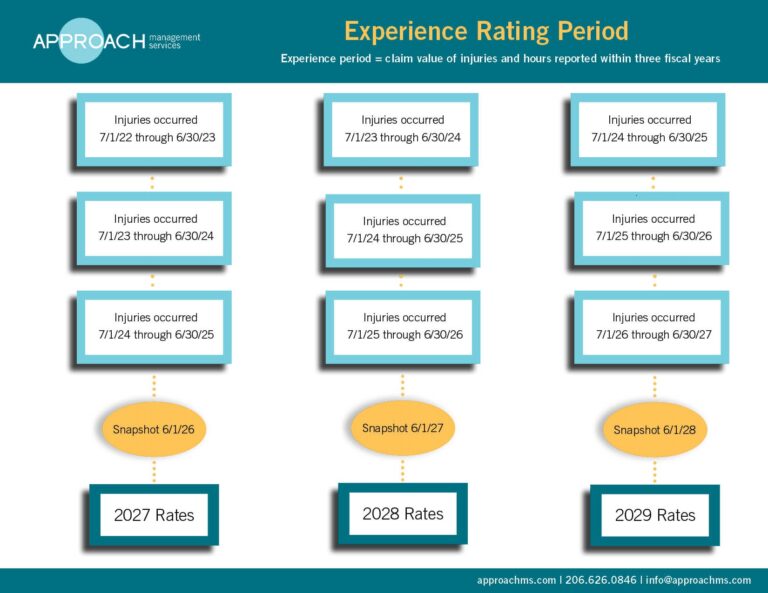
L&I determines each employers’ EMR by taking into account three prior years of claims history.
A snapshot of your claim costs is taken every June 1st to calculate your upcoming premium rate.
The calculated Experience Modification Rate is effective every January 1st.
Date of Injury Years Impacted
7/1/23- 6/30/24 2026, 2027, 2028
7/1/24- 6/30/25 2027, 2028, 2029
7/1/25- 6/30/26 2028, 2029, 2030
7/1/26- 6/30/27 2029, 2030, 2031
7/1/27- 6/30/28 2030, 2031, 2032
DOWNLOAD THIS FLYER
How is EMR Calculated?
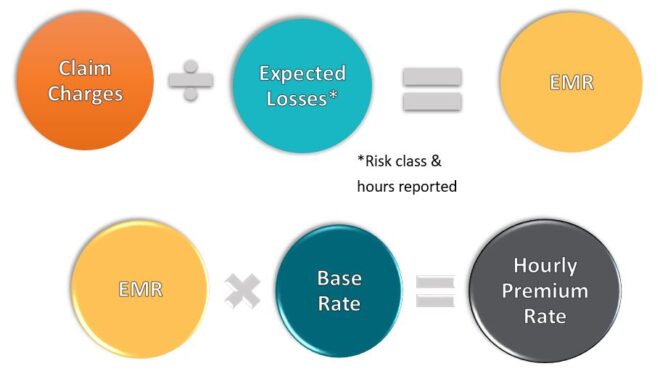
If we can reduce it to its simplest form, claim charges divided by expected losses = EMR.
Where do expected losses come from? The hours (or board feet for drywall) you reported in the various risk classes under which you report hours to L&I.
And then, your EMR is used as a multiplier of your base rate, resulting in your hourly premium rates for the calendar year.
This is a simplified EMR Calculation:
Experience Modification Rates: 0-10
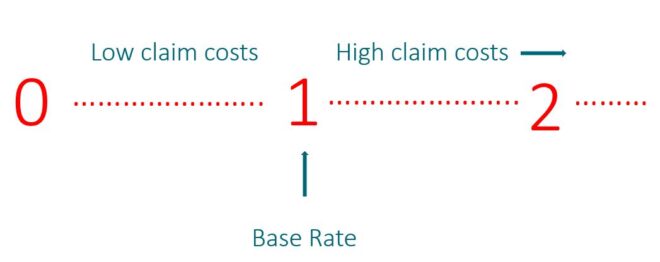
The 0, 1, and 2 here represent EMRs.
At an EMR of 1.000, your rates will be equal to the base rates. Every brand new business is set at 1.000. This is considered the average.
If your EMR is below 1.000 due to low claim costs, you will be paying less than the base rate for the risk classes you report under. You are preforming better than average.
But if your EMR is over 1.000 due to high claim costs, you will be paying more than the base rate for your risk classes.
Case Study
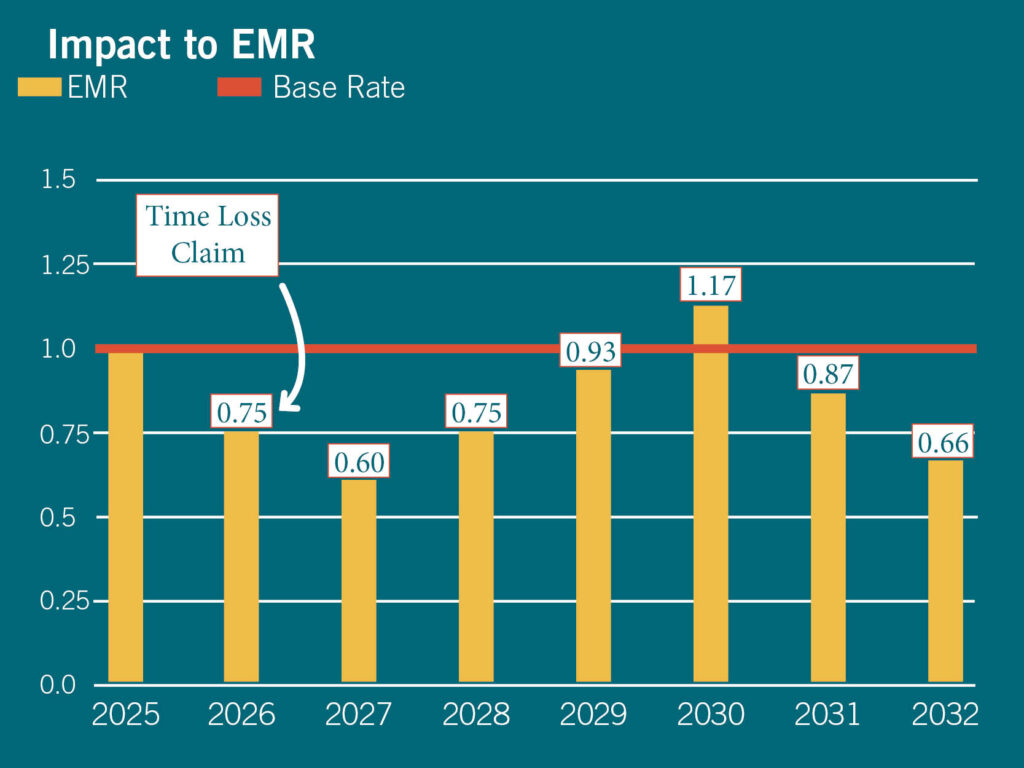
This case study is of a mid-size business (around $50,000 in premium) who has never had a workplace injury until 2026.
In 2026, this company had one injury and this employee received time loss from L&I (an indemnity claim).
Following 2026, the company does not have any other workplace injuries. The next graph displays the effect one indemnity claim (time loss) has on a company’s EMR.
What are Base Rates?
Annually, L&I sets the base rates for each risk class. It’s comprised of three parts:
- Accident fund
This fund pays for all non-medical claim costs.
- Medical aid fund
This fund pays for medical care, some vocational services, and the Stay-At-Work Program.
- Supplemental pension fund
This fund covers second injury fund claims and cost of living adjustment for pensions.
Medical-Only Discount
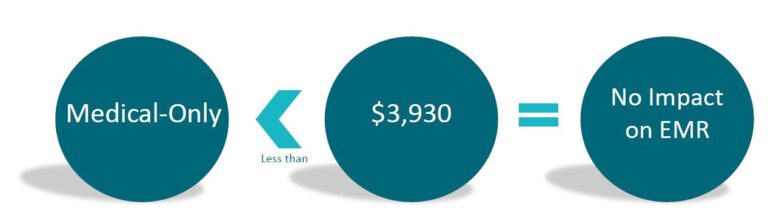
For rating year 2025, L&I will reduce the cost of medical-only claims by up to $3,930.
This deduction is twice the average incurred cost for medical-only claims.
Medical-only claims below this threshold do not impact your EMR.
Claim-Free Discount
If your business has only medical-only claims or no claims within the experience period, you qualify for the claim-free discount.
Businesses with a compensable claim (i.e. time loss, loss of earning power, or permanent partial disability) do not qualify for the claim-free discount.
Additional EMR Factors
Considerations regarding EMR calculations:
Common ownership: Separate subaccounts shall be combined for EMR purposes when the same person and or/single corporation owns a majority interest.
Change of business ownership: Past loss experience shall transfer to the new ownership.